
Corporate Downgrades Reach Alarming Levels
The U.S. corporate debt market is showing signs of strain as credit rating downgrades have surged to their highest level since early 2021. According to data from JPMorgan Chase & Co., the second quarter of 2025 saw approximately $94 billion in high-grade U.S. debt downgraded. This figure surpassed the $78 billion in upgrades during the same period, marking a significant shift in corporate financial health.
JPMorgan strategists, including Eric Beinstein and Silvi Mantri, revealed in a recent report that this reversal in the upgrade-downgrade trend is raising concerns among investors and analysts. With economic uncertainty looming, more companies are at risk of facing downgrades in the coming months.
Economic Pressures Mount
The surge in downgrades highlights the mounting pressure on U.S. companies as they navigate a challenging economic landscape. Rising interest rates, persistent inflation, and slowing consumer demand have all contributed to declining corporate performance. These macroeconomic headwinds are forcing firms to reassess their debt obligations, with many struggling to maintain optimal credit ratings.
“The market is re-evaluating risk as cost pressures and weaker earnings weigh on company balance sheets,” said Beinstein. “We expect this trend to continue if economic conditions don’t stabilize soon.”
Implications for Corporate Debt Valuations
The spike in downgrades is sparking fresh debate over the valuation of corporate debt. For much of the past decade, investors have poured into corporate bonds in search of higher yields, pushing prices up and spreads down. But with downgrades outpacing upgrades, the market may need to reprice risk more accurately.
“There’s a growing disconnect between credit ratings and bond prices,” said a credit analyst at a major investment bank. “Investors may have to brace for increased volatility as more downgrades materialize.”
This shift could lead to wider credit spreads, particularly in sectors most vulnerable to economic downturns, such as real estate, construction, and discretionary consumer goods.
Sectors Most Affected
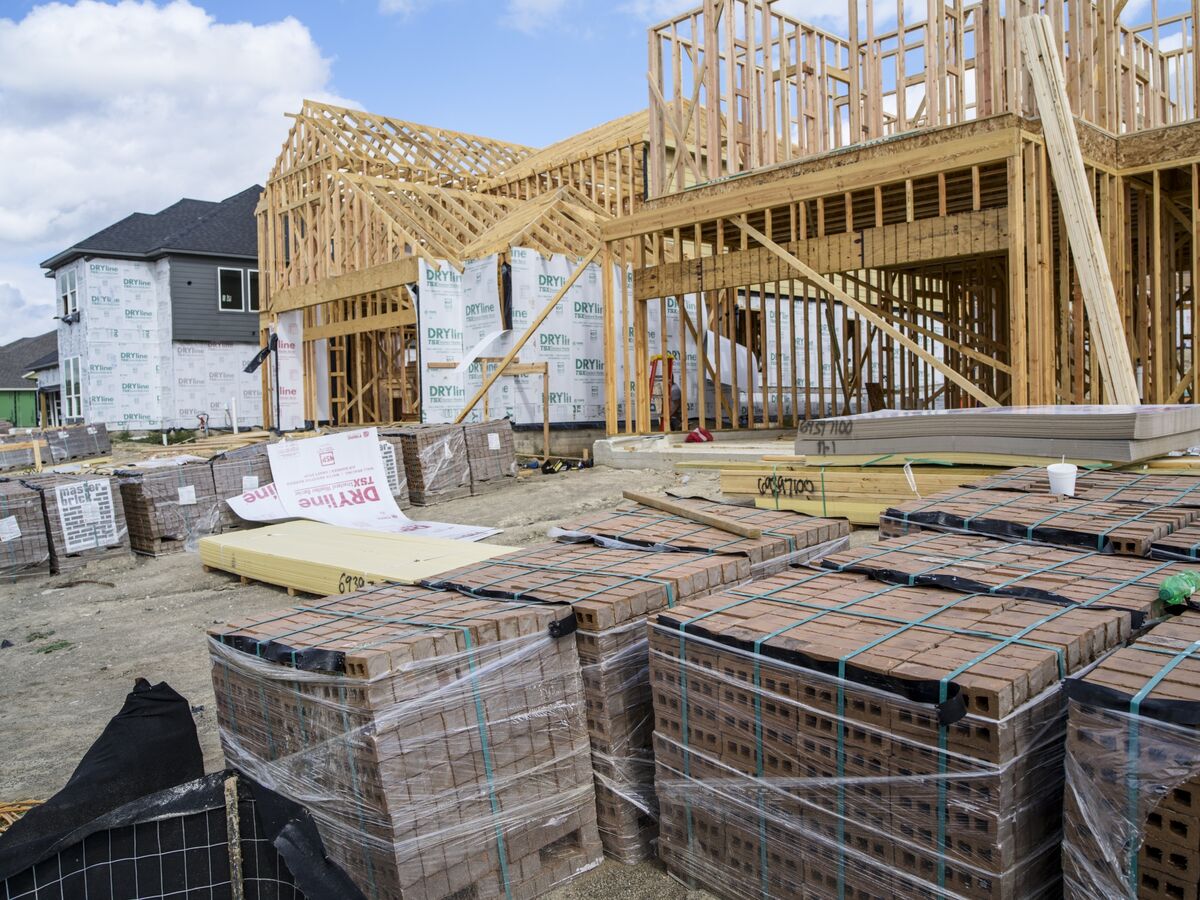
While the downgrade trend is widespread, certain sectors are feeling the impact more acutely. The construction and materials industry, for instance, is under pressure due to higher financing costs and supply chain disruptions. In Buda, Texas, for example, new home developments are facing delays and budget overruns, further straining company finances.
Other industries, such as retail and technology, are also experiencing challenges. As consumers reduce spending, retail companies with large debt loads are struggling to maintain revenue streams. In the tech sector, slower growth and reduced venture capital funding are putting pressure on profitability and balance sheets.
Investor Sentiment Shifts
Investor sentiment is beginning to shift as the reality of increased downgrade risks sets in. Fund managers are becoming more selective, favoring companies with strong fundamentals and manageable debt levels. Some are reallocating assets into safer investments like Treasuries or investment-grade bonds with stable outlooks.
“We’re definitely more cautious now,” said a portfolio manager at a large pension fund. “We’re closely analyzing credit metrics and reducing exposure to companies that might face ratings pressure.”
This more conservative approach could have a ripple effect across the market, potentially limiting access to capital for weaker firms and increasing borrowing costs.
What Lies Ahead
Looking forward, analysts expect the downgrade trend to persist unless there is a material improvement in economic indicators. Corporate earnings reports in the coming quarters will be closely watched for signs of resilience or further deterioration. Meanwhile, the Federal Reserve’s monetary policy decisions will play a critical role in shaping credit conditions.
JPMorgan’s strategists caution that if the economy slips further, the volume of downgrades could accelerate, putting even more pressure on corporate borrowers.
“We could be in the early stages of a broader credit cycle,” said Mantri. “Companies that have relied heavily on cheap debt will need to adapt quickly or risk facing further rating actions.”
Conclusion
The recent surge in credit rating downgrades is a clear signal that parts of the U.S. corporate sector are under stress. With economic uncertainty on the horizon, investors, analysts, and companies alike must navigate a more complex and risk-sensitive environment. The next few quarters will be crucial in determining whether this trend is a temporary correction or the start of a prolonged credit downturn.
This article is inspired by content from Original Source. It has been rephrased for originality. Images are credited to the original source.