
Supreme Court Ruling Narrows Scope of Car Finance Payouts
The UK’s Supreme Court has issued a pivotal ruling that significantly reduces the potential compensation car finance companies may owe to customers. While this decision offers a measure of relief to finance firms and banks, it does not fully absolve them of responsibility. Experts suggest that compensation payouts, although lower than initially feared, could still run into the billions.
The ruling has diminished the likelihood of a government bailout, easing concerns of a financial tsunami that could have cost the industry as much as £40 billion. However, the Financial Conduct Authority (FCA) continues to investigate possible redress scenarios for customers affected by unfair lending practices.
Background: Commission Payments Under Scrutiny
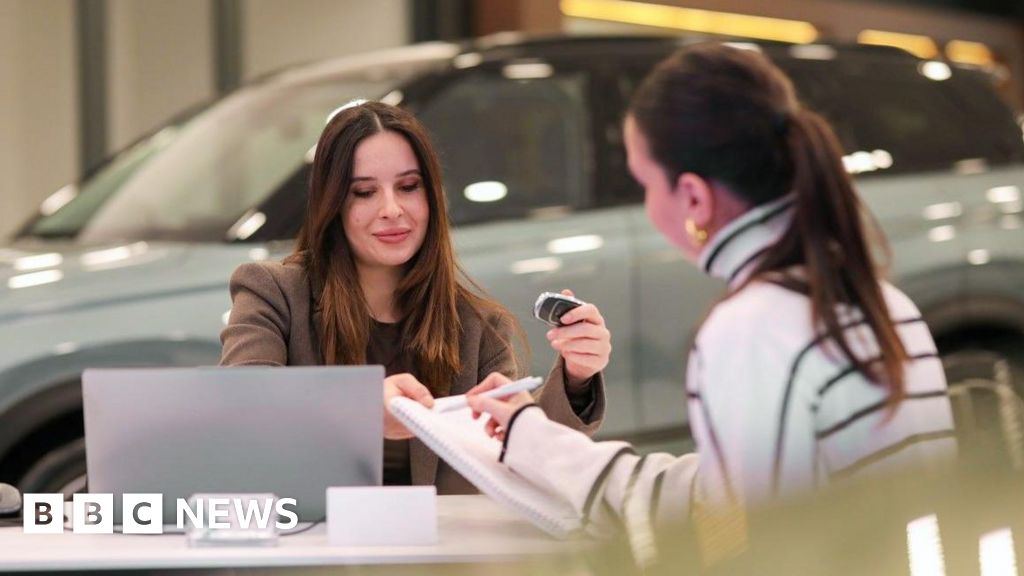
The controversy began when several car buyers discovered that their finance agreements included undisclosed commissions paid by lenders to dealers. These buyers argued that such payments were either bribes or secret commissions, leading to unfair financial arrangements. In October, the Court of Appeal supported this argument, asserting that these commissions were unlawful without the buyer’s informed consent.
The Appeal Court also suggested that car dealers had a fiduciary duty to act in the best interest of their customers—a ruling that could have opened the floodgates for compensation claims from millions of consumers. The finance industry feared this interpretation would not only impact car loans but also extend to other consumer finance agreements, drastically increasing their liability.
Supreme Court Limits Broad Claims
In contrast, the Supreme Court dismissed the idea that dealers owed a fiduciary duty to buyers. Lord Reed, President of the Court, stated that car dealers inherently have personal interests in the finance agreements they facilitate and that expecting them to act with a “single minded duty of loyalty” to consumers was unrealistic.
This judgment effectively blocks a wide array of potential compensation claims based on the fiduciary duty argument. However, the court did uphold one specific claim brought by Marcus Johnson, a factory worker. The court found his finance agreement to be “unfair” under the Consumer Credit Act due to a large undisclosed commission and misleading information about the lender-dealer relationship.
Legal analysts believe this case could serve as a precedent for future claims, particularly where commissions are considered egregiously large and undisclosed.
Focus Shifts to Discretionary Commission Agreements
Although the Supreme Court has narrowed the scope for claims, another unresolved issue remains: Discretionary Commission Agreements (DCAs). These arrangements allowed car dealers to set interest rates within a specified range, earning higher commissions for charging higher rates—often without the customer’s knowledge.
The FCA banned DCAs in 2021 but is now considering whether to introduce a redress scheme for consumers affected by these deals. If implemented, the scheme could lead to substantial compensation claims, although the exact amount remains uncertain.
Financial experts like Richard Barnwell, a partner at BDO, estimate potential redress costs could range from £5 billion to as much as £13 billion. He noted, “We believe there is still a potential for redress, for example, if discretionary commission arrangements are deemed to be an unfair relationship.”
Industry Reacts to Reduced Liability
Despite the Supreme Court’s favorable ruling for lenders, the car finance sector remains cautious. Martin Lewis, founder of the MoneySavingExpert website, commented, “The Supreme Court has certainly narrowed the number of people who will be able to reclaim car finance. I think you’re probably talking the lower end of £10bn, as opposed to £40bn.”
Even at £10 billion, the compensation figure remains substantial. However, the ruling has likely prevented a chaotic rush of claims and reduced the risk of retroactive government intervention. A Treasury spokesperson noted that they would “work with regulators and industry to understand the impact for both firms and consumers.”
Sources close to the matter suggest that the government is now unlikely to introduce retrospective legislation aimed at shielding financial firms from liability.
Looking Ahead: Potential Outcomes
In summary, while the Supreme Court’s decision has significantly reduced the compensation liabilities for car finance providers, the industry is not entirely off the hook. The FCA’s upcoming decisions regarding DCAs and potential consumer redress schemes will be crucial in determining the final financial impact on lenders.
Consumers who believe they may have been misled or charged unfair interest rates due to undisclosed commissions are still encouraged to review their finance agreements and seek legal advice. The landscape of car finance compensation may have changed, but it is far from settled.
This article is inspired by content from Original Source. It has been rephrased for originality. Images are credited to the original source.