
Introduction: A Strategic Shift in U.S. Digital Finance
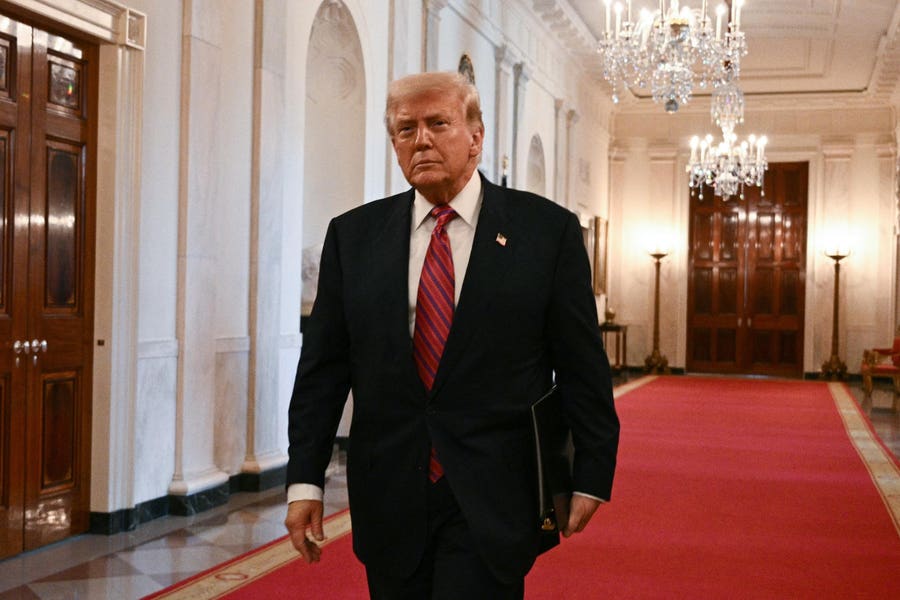
On July 18, 2025, President Donald Trump signed the GENIUS Act (Guiding and Establishing National Innovation for US Stablecoins Act), marking a pivotal moment in America’s journey toward digital financial innovation. This legislation formally recognizes stablecoins—cryptocurrencies tied to stable assets such as the U.S. dollar or government bonds—and signifies a broader national commitment to modernizing the financial infrastructure.
Following President Biden’s 2022 executive order on digital assets, the U.S. Treasury released a comprehensive policy roadmap titled Strengthening American Leadership in Digital Financial Technology. The report outlines coordinated strategies for federal agencies and sets the stage for transformative changes across the banking ecosystem.
From Fragmentation to National Coordination
Historically, U.S. innovation in financial technology has been marked by fragmentation across states, regulatory bodies, and platforms. This disjointed approach has led to inefficiencies, limited experimentation, and inconsistencies in consumer protections and data protocols.
The Treasury’s report underscores the urgency of developing a synchronized, national strategy that harmonizes public and private sector efforts. For banks, this means aligning innovation initiatives with federal infrastructure and policy goals to enhance resilience and global competitiveness.
Faster Payments: The Foundation of a Digital Economy
According to the Treasury, real-time payments form the backbone of a modern financial system. The government urges financial institutions to adopt faster payment systems and upgrade legacy infrastructure, especially for smaller banks that face technical and financial hurdles.
Despite progress through platforms like FedNow and The Clearing House’s RTP network, adoption remains uneven. A 2025 report from Cornerstone Advisors reveals that only 45% of banks and 38% of credit unions offer real-time payment capabilities, with most limited to receiving, not sending, instant payments.
For banks, the implication is clear: those failing to integrate instant payments risk falling behind in customer experience, liquidity management, and fraud prevention.
Digital Identity: The Missing Pillar
One of the most critical yet under-addressed challenges in U.S. financial innovation is the lack of a secure, interoperable digital identity system. Without a standardized identity framework, banks face higher fraud risks, cumbersome onboarding processes, and limited automation potential.
The Treasury calls for investment in digital identity infrastructure as a core element of public digital infrastructure. While private companies have attempted proprietary solutions, none have gained widespread adoption due to the absence of regulatory mandates.
Banks are urged to support public-private partnerships, participate in pilot programs, and advocate for scalable identity standards. This is not only a security upgrade but also a key to unlocking seamless digital experiences.
Open Banking and Data Infrastructure
The U.S. has taken a market-led approach to data access, relying on data aggregators to mediate between banks and third-party applications. This has created friction over data privacy, user control, and liability, exacerbated by inconsistent rulemaking by agencies like the Consumer Financial Protection Bureau (CFPB).
By contrast, nations such as the UK and EU have implemented formal open banking regimes with standardized APIs and data formats. The Treasury’s roadmap suggests a shift toward a national strategy for data, promoting secure APIs and consumer-centric consent policies.
Banks should view open banking not as a regulatory burden, but as a competitive advantage in building trust, enhancing transparency, and creating integrated financial ecosystems.
Global Competition: The Risk of Falling Behind
While the U.S. has hesitated, global competitors like China and the European Union have forged ahead with digital currencies, identity systems, and payments modernization. Smaller countries such as Singapore and New Zealand have also made strategic investments in infrastructure and regulatory innovation.
The Treasury warns that without coordinated action, the U.S. risks ceding leadership in digital finance. Banks, particularly those with international exposure, must assess how global regulatory alignment and infrastructure shifts may impact their operations and competitive positioning.
What Banks Should Do Now
While the Treasury’s report does not mandate specific actions for banks, it offers a clear directional signal. Banks that aim to lead must proactively align with the emerging digital finance landscape. Key steps include:
- Adopt real-time payments: Embrace platforms like FedNow and RTP, modernize internal systems, and educate stakeholders on their benefits.
- Invest in secure API frameworks: Enhance consent management, partner with fintechs, and leverage APIs for new services.
- Support digital identity development: Participate in pilots and align internal processes with best practices in identity verification.
- Revamp data governance: Ensure data is secure, accurate, and accessible for both internal use and authorized third-party integration.
Digital Finance: A Business Imperative
Digital transformation is no longer just a technology initiative—it’s a core business strategy. Boards and executives must evaluate how their institutions are preparing for a digital-first future and how they will compete with fintechs, tech giants, and global financial institutions.
The Treasury’s roadmap represents a turning point in U.S. financial modernization. Banks that embrace this moment will be better positioned to lead, innovate, and thrive in the next chapter of global finance.
This article is inspired by content from Original Source. It has been rephrased for originality. Images are credited to the original source.